

The entire purpose of the Medicare system, including Medicare Advantage plans, is to get eligible participants the medical care that they need. Participants enrolled in Medicare Advantage plans are entitled to the same care and coverage as those enrolled in Traditional Medicare. They may get a few more benefits, but they are not supposed to get any less. Unfortunately, that is not the way it is actually working.
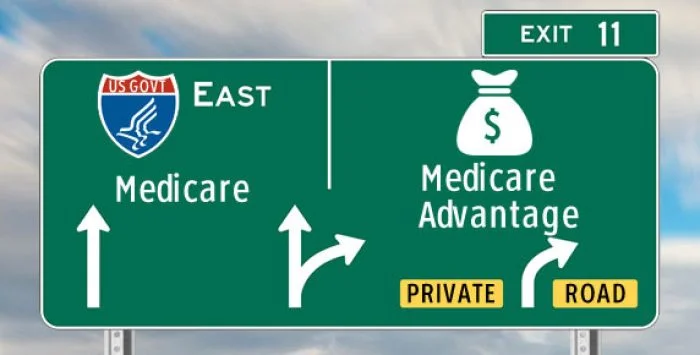
In Traditional Medicare, the federal government pays for a participant’s care. In a Medicare Advantage plan, the insurance company which is sponsoring the plan receives a fixed amount from the federal government, which it is to use to pay for the medical care of the participant. Any money not spent on care for the participant goes into the pocket of the sponsoring insurance company. While the administrators of Traditional Medicare have no financial incentive to deny care for participants, the private insurance companies sponsoring Medicare Advantage plans do have a financial interest in reducing the amount of care their participants receive.
Under the guise of preventing fraud and assuring that its participants receive quality care, the big insurance companies that sponsor Medicare Advantage plans require prior permission for many expenditures, especially large ones. Not only do they require prior permission, which often delays the care a participant needs, they frequently deny the permission. They deny permission for procedures and care which are routinely approved for Traditional Medicare participants under the same circumstances.
While it is true that a Medicare Advantage participant has the right to appeal a denial, many do not and, for those that do, it takes time which may make the treatment in question too late to help.
Here is the kicker. When Medicare Advantage participants do appeal, they almost always win. The problem is most acute when the care at issue is nursing home admission or admission to a long-term care facility, two care decisions that can be costly for an insurance company. The Office of the Inspector General of the Department of Health and Human Services, which oversees Medicare, has taken notice.
Two recent reports by the Inspector General found that the three largest insurance companies on average denied about 13% of the requests for admission to a nursing home. Fewer than one in five appealed the decision. When participants did appeal, they won over 92% of the appeals involving the three largest companies. For United Health Group, the rate was over 99%. For CVS Health/Aetna, the rate was 98%. Humana was the most successful of the big three and it still lost over 92% of the time there was an appeal. This means that the denials by these big companies were almost always wrong. They were denying their participants the care to which they were entitled and were putting the money into their own pockets. Eighty percent of the time they made such a denial, they got to keep the money because there was no appeal. The companies bank on this to the detriment of their participants.
Every year, people eligible for Medicare coverage get an opportunity to start over. They can select a Medicare Advantage plan or they can select Traditional Medicare, even if they are currently enrolled in a Medicare Advantage plan. If you are eligible to make this choice, you should be sure to ask yourself whether you would prefer to have coverage questions decided by someone with no financial stake in the answer or someone who will make money out of denying you the care you are entitled to receive. Seems like a no brainer to me.


